Rental Yield.
Rental yield shows how much rental income a property generates compared with its value. Learn the formula, examples, and how investors use it..
Rental yield is the annual rental income generated by a property expressed as a percentage of its purchase price or current market value.
In simple terms, the rental yield definition explains how much rental income a property generates relative to its value. It is one of the most useful measurements for property investors because it provides a quick way to compare the income potential of different properties.
For example, if a property is worth AED 1,000,000 and produces AED 72,000 in annual rent, the gross rental yield is 7.2%.
Investors often use rental yield as an initial screening tool before carrying out a deeper financial analysis.
You can estimate the rental yield of a property using the Rental Yield Calculator.
Why Rental Yield Matters
Rental yield helps investors understand how efficiently a property generates rental income compared with its value.
It can be useful when comparing:
Two properties in the same neighborhood
Different areas within one city
Apartments and villas
Established and emerging property markets
Rental-focused investment opportunities
However, rental yield should not be used alone when deciding whether a property is a good investment.
A property with a high yield may also have higher maintenance costs, weaker resale demand, more tenant turnover, or greater vacancy risk.
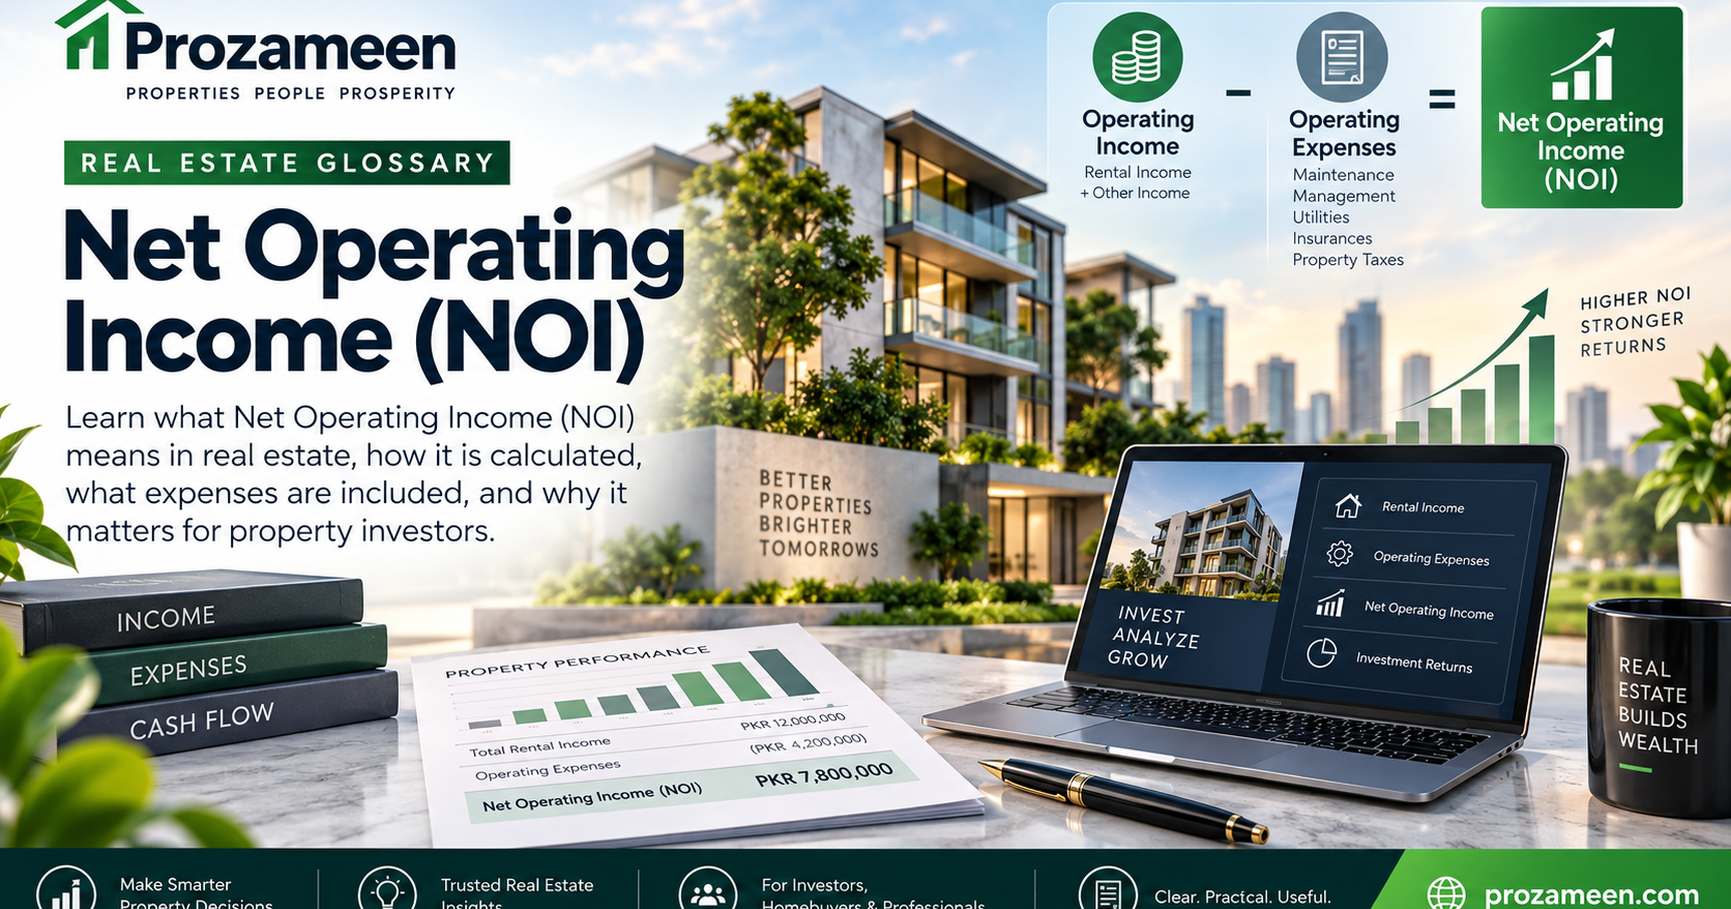
For a more complete investment analysis, investors should also consider Net Operating Income, capitalization rate, cash flow, financing costs, and long-term appreciation potential.
You can learn more about operating income in the Net Operating Income (NOI) Glossary.
You can also compare income performance using the Capitalization Rate (Cap Rate) Glossary.
Gross Rental Yield
Gross rental yield measures annual rental income before property-related expenses are deducted.
It is useful when an investor wants a quick comparison between different properties.
Gross Rental Yield Formula
Gross Rental Yield (%) = Annual Rental Income ÷ Property Value × 100
Example:
Property value: AED 1,000,000
Monthly rent: AED 6,000
Annual rent: AED 72,000
Calculation:
72,000 ÷ 1,000,000 × 100 = 7.2%
The gross rental yield is 7.2%.
Net Rental Yield
Net rental yield measures the property's rental return after relevant operating expenses are deducted.
It usually provides a more realistic picture than gross yield because property ownership involves costs.
Common expenses may include:
Service charges
Maintenance
Property management fees
Insurance
Vacancy costs
Leasing costs
Repairs
Owners' association fees
Net Rental Yield Formula
Net Rental Yield (%) = (Annual Rental Income − Annual Property Expenses) ÷ Property Value × 100
Example:
Annual rent: AED 72,000
Annual property expenses: AED 18,000
Net rental income: AED 54,000
Property value: AED 1,000,000
Calculation:
54,000 ÷ 1,000,000 × 100 = 5.4%
The property's estimated net rental yield is 5.4%.
This shows why investors should not rely only on advertised gross yields.
What Is a Good Rental Yield?
There is no single rental yield that is considered good in every market.
A reasonable yield depends on factors such as:
Location
Property type
Purchase price
Rental demand
Vacancy rates
Property condition
Service charges
Financing costs
Local supply
Expected appreciation
A lower-yield property in a strong location may still perform well because of stable tenant demand and long-term value growth.
A higher-yield property may offer stronger income but could also involve more risk.
Before buying, investors should evaluate the wider property market using the How to Evaluate a Property Market Before Investing guide.
Rental Yield and Property Expenses
Property expenses can make a major difference between the advertised yield and the return an investor actually receives.
For example:
Gross annual rent: AED 80,000
Operating expenses: AED 20,000
Net rental income: AED 60,000
If the property value is AED 1,000,000:
Gross yield = 8%
Estimated net yield = 6%
That 2% difference can significantly affect investment performance over several years.
Investors can also review ownership-related costs using the Property Ownership Cost Planner.
Rental Yield and Vacancy
Rental yield calculations often assume that a property remains occupied throughout the year.
In reality, vacancies can reduce annual rental income.
If a property normally earns AED 6,000 per month but remains vacant for one month:
Expected annual rent:
AED 72,000
Actual annual rent:
AED 66,000
On an AED 1,000,000 property:
Expected gross yield:
7.2%
Actual gross yield:
6.6%
This is why realistic rental assumptions are important.
Rental Yield and Capital Appreciation
Rental yield measures income.
Capital appreciation measures how much the property may increase in value over time.
These are different sources of return.
Some investors prefer properties with stronger rental income.
Others may accept a lower rental yield if they believe the property has stronger long-term appreciation potential.
The best approach depends on the investor's objective.
For broader market comparison, investors can review Global & Regional Real Estate Market Trends 2026.
Rental Yield and Mortgage Costs
Rental yield does not automatically show whether a property will produce positive cash flow after financing.
An investor may have to pay:
Mortgage interest
Principal repayments
Bank fees
Insurance
Other financing costs
A property can show a healthy rental yield but still produce weak cash flow if mortgage costs are high.
Investors can estimate loan payments using the Mortgage / EMI Calculator.
Rental Yield in Dubai
Rental yield is widely used when comparing investment properties in Dubai because different communities can have very different price and rent levels.
An affordable apartment area may offer a higher percentage yield than a premium waterfront district.
However, premium locations may offer stronger resale demand, better tenant stability, or greater capital appreciation potential.
Investors considering Dubai can review the Dubai Real Estate Investment Guide 2026.
They can also explore the Invest in Dubai Property Complete Investor Guide.
How Investors Should Use Rental Yield
Rental yield is most useful as an initial comparison metric.
A complete investment decision should also consider:
Net Operating Income
Cap rate
Cash flow
Property condition
Tenant demand
Vacancy risk
Service charges
Financing
Future supply
Capital appreciation
Resale potential
For a broader property evaluation, investors can also use the Property Deal Analyzer.
Common Rental Yield Mistakes
Using Asking Rent Instead of Realistic Rent
Advertised rents may not always reflect what tenants are actually willing to pay.
Ignoring Vacancy
Assuming twelve months of uninterrupted rent can overstate expected returns.
Ignoring Operating Costs
Service charges, management fees, maintenance and repairs can reduce net yield.
Comparing Different Markets Without Context
A 6% yield in one city may carry a very different level of risk from a 6% yield in another market.
Choosing a Property Only Because of High Yield
High yield alone does not guarantee a good investment.
Investors should also consider location, demand, condition and resale potential.
Rental yield is the annual rental income generated by a property expressed as a percentage of its purchase price or current market value.
In simple terms, the rental yield definition explains how much rental income a property generates relative to its value. It is one of the most useful measurements for property investors because it provides a quick way to compare the income potential of different properties.
For example, if a property is worth AED 1,000,000 and produces AED 72,000 in annual rent, the gross rental yield is 7.2%.
Investors often use rental yield as an initial screening tool before carrying out a deeper financial analysis.
You can estimate the rental yield of a property using the Rental Yield Calculator.
Why Rental Yield Matters
Rental yield helps investors understand how efficiently a property generates rental income compared with its value.
It can be useful when comparing:
- Two properties in the same neighborhood
- Different areas within one city
- Apartments and villas
- Established and emerging property markets
- Rental-focused investment opportunities
However, rental yield should not be used alone when deciding whether a property is a good investment.
A property with a high yield may also have higher maintenance costs, weaker resale demand, more tenant turnover, or greater vacancy risk.
For a more complete investment analysis, investors should also consider Net Operating Income, capitalization rate, cash flow, financing costs, and long-term appreciation potential.
You can learn more about operating income in the Net Operating Income (NOI) Glossary.
You can also compare income performance using the Capitalization Rate (Cap Rate) Glossary.
Gross Rental Yield
Gross rental yield measures annual rental income before property-related expenses are deducted.
It is useful when an investor wants a quick comparison between different properties.
Gross Rental Yield Formula
Gross Rental Yield (%) = Annual Rental Income ÷ Property Value × 100
Example:
- Property value: AED 1,000,000
- Monthly rent: AED 6,000
- Annual rent: AED 72,000
Calculation:
72,000 ÷ 1,000,000 × 100 = 7.2%
The gross rental yield is 7.2%.
Net Rental Yield
Net rental yield measures the property's rental return after relevant operating expenses are deducted.
It usually provides a more realistic picture than gross yield because property ownership involves costs.
Common expenses may include:
- Service charges
- Maintenance
- Property management fees
- Insurance
- Vacancy costs
- Leasing costs
- Repairs
- Owners' association fees
Net Rental Yield Formula
Net Rental Yield (%) = (Annual Rental Income − Annual Property Expenses) ÷ Property Value × 100
Example:
- Annual rent: AED 72,000
- Annual property expenses: AED 18,000
- Net rental income: AED 54,000
- Property value: AED 1,000,000
Calculation:
54,000 ÷ 1,000,000 × 100 = 5.4%
The property's estimated net rental yield is 5.4%.
This shows why investors should not rely only on advertised gross yields.
What Is a Good Rental Yield?
There is no single rental yield that is considered good in every market.
A reasonable yield depends on factors such as:
- Location
- Property type
- Purchase price
- Rental demand
- Vacancy rates
- Property condition
- Service charges
- Financing costs
- Local supply
- Expected appreciation
A lower-yield property in a strong location may still perform well because of stable tenant demand and long-term value growth.
A higher-yield property may offer stronger income but could also involve more risk.
Before buying, investors should evaluate the wider property market using the How to Evaluate a Property Market Before Investing guide.
Rental Yield and Property Expenses
Property expenses can make a major difference between the advertised yield and the return an investor actually receives.
For example:
- Gross annual rent: AED 80,000
- Operating expenses: AED 20,000
- Net rental income: AED 60,000
If the property value is AED 1,000,000:
Gross yield = 8%
Estimated net yield = 6%
That 2% difference can significantly affect investment performance over several years.
Investors can also review ownership-related costs using the Property Ownership Cost Planner.
Rental Yield and Vacancy
Rental yield calculations often assume that a property remains occupied throughout the year.
In reality, vacancies can reduce annual rental income.
If a property normally earns AED 6,000 per month but remains vacant for one month:
Expected annual rent:
AED 72,000
Actual annual rent:
AED 66,000
On an AED 1,000,000 property:
Expected gross yield:
7.2%
Actual gross yield:
6.6%
This is why realistic rental assumptions are important.
Rental Yield and Capital Appreciation
Rental yield measures income.
Capital appreciation measures how much the property may increase in value over time.
These are different sources of return.
Some investors prefer properties with stronger rental income.
Others may accept a lower rental yield if they believe the property has stronger long-term appreciation potential.
The best approach depends on the investor's objective.
For broader market comparison, investors can review Global & Regional Real Estate Market Trends 2026.
Rental Yield and Mortgage Costs
Rental yield does not automatically show whether a property will produce positive cash flow after financing.
An investor may have to pay:
- Mortgage interest
- Principal repayments
- Bank fees
- Insurance
- Other financing costs
A property can show a healthy rental yield but still produce weak cash flow if mortgage costs are high.
Investors can estimate loan payments using the Mortgage / EMI Calculator.
Rental Yield in Dubai
Rental yield is widely used when comparing investment properties in Dubai because different communities can have very different price and rent levels.
An affordable apartment area may offer a higher percentage yield than a premium waterfront district.
However, premium locations may offer stronger resale demand, better tenant stability, or greater capital appreciation potential.
Investors considering Dubai can review the Dubai Real Estate Investment Guide 2026.
They can also explore the Invest in Dubai Property Complete Investor Guide.
How Investors Should Use Rental Yield
Rental yield is most useful as an initial comparison metric.
A complete investment decision should also consider:
- Net Operating Income
- Cap rate
- Cash flow
- Property condition
- Tenant demand
- Vacancy risk
- Service charges
- Financing
- Future supply
- Capital appreciation
- Resale potential
For a broader property evaluation, investors can also use the Property Deal Analyzer.
Common Rental Yield Mistakes
Using Asking Rent Instead of Realistic Rent
Advertised rents may not always reflect what tenants are actually willing to pay.
Ignoring Vacancy
Assuming twelve months of uninterrupted rent can overstate expected returns.
Ignoring Operating Costs
Service charges, management fees, maintenance and repairs can reduce net yield.
Comparing Different Markets Without Context
A 6% yield in one city may carry a very different level of risk from a 6% yield in another market.
Choosing a Property Only Because of High Yield
High yield alone does not guarantee a good investment.
Investors should also consider location, demand, condition and resale potential.