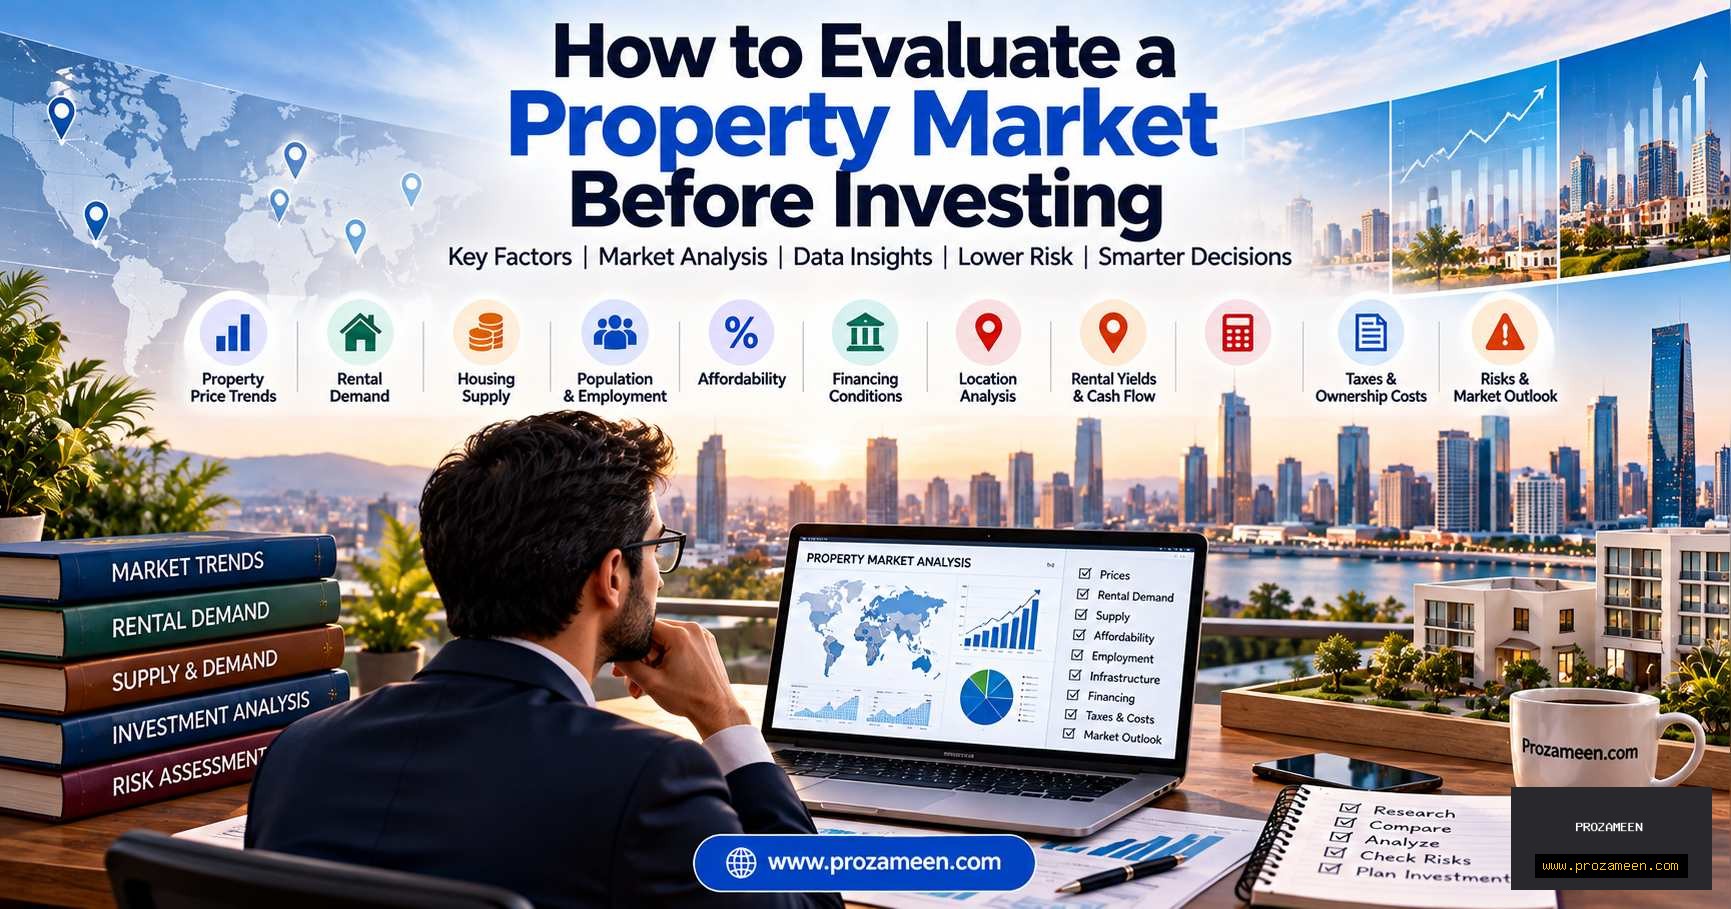
How to Evaluate a Property Market Before Investing
A good property can still become a poor investment if it is purchased in the wrong market, at the wrong price or under weak economic conditions.
That is why experienced investors do not start by asking, “Which property should I buy?”
They start with a broader question:
“Is this property market worth investing in at all?”
Evaluating a property market means understanding the forces that influence prices, rents, demand, supply, financing and future resale potential.
The goal is not to predict the future perfectly. No investor can do that.
The goal is to build enough evidence to understand whether a market is supported by healthy fundamentals or mainly by short-term excitement.
For a broader view of international market conditions, Prozameen’s Global Real Estate Market Outlook 2026 provides useful context before you begin analysing an individual market.
Start With the Big Picture
Before examining a particular neighbourhood or property, understand the wider market.
A property market is influenced by many forces at the same time.
Employment affects household income.
Interest rates affect mortgage affordability.
New construction affects housing supply.
Population growth influences demand.
Rental conditions affect investor income.
Economic confidence affects buying activity.
A strong property market usually has several supportive factors working together rather than relying on only one.
For example, rapid price growth alone does not necessarily mean a market is healthy. Prices may be rising because supply is limited, because borrowing has become easier or simply because buyers are speculating.
The reason behind the movement matters.
Study Property Price Trends
One of the first things investors usually look at is property prices.
Historical price data can help you understand whether a market has been rising, falling or remaining relatively stable. However, price growth needs careful interpretation because past performance does not guarantee future appreciation.
Ask whether prices are increasing because of:
Population growth
More households may be competing for limited housing, which can support demand and place upward pressure on prices.
Employment growth
Stronger employment and higher household incomes may improve purchasing power and support housing demand.
Limited supply
A shortage of available homes, especially in areas with strong demand, can contribute to higher property prices.
Lower financing costs
Cheaper mortgages can increase buyer purchasing power and make property more affordable for a wider group of buyers.
Investor demand
Large amounts of investment capital can increase competition for property, although investor-driven price growth may not always be sustainable.
When reviewing a market, compare:
- Average property prices over the past 5 to 10 years
- Recent annual and quarterly price changes
- Rental yields relative to purchase prices
- New housing supply and construction activity
- Population and employment trends
- Infrastructure development
- Financing conditions
Do not assume that a market with the fastest historical price growth automatically offers the strongest future opportunity.
To explore different long-term property-growth assumptions, use the Property Appreciation Calculator. It can help estimate a possible future property value using the current value, an assumed annual appreciation rate and a selected holding period.
The result should be treated as a planning scenario rather than a prediction. Actual property values may rise, remain stable or decline depending on market conditions.
Prozameen’s Global Property Price Trends Report 2026 can also provide broader context when comparing price movements across different markets.
Compare Property Prices With Local Income
Property prices should not be viewed in isolation.
A market can become expensive even while prices continue rising.
One useful question is:
Can local households realistically afford these properties?
If property prices rise much faster than household incomes, affordability can deteriorate.
That may eventually affect:
Buyer demand
Fewer households may qualify for mortgages.
Rental demand
More people may remain renters.
Market stability
Future price growth may become more dependent on investors or high-income buyers.
The relationship between income, property prices and financing is explored further in Prozameen’s Global Housing Affordability Report 2026.
Understand Rental Demand
For an income-focused investor, rental demand is one of the most important market indicators.
A property may look inexpensive, but if there are few tenants, the investment can struggle.
Strong rental demand may be supported by employment centres, universities, tourism, migration, transport links or limited housing availability.
Ask who is actually renting in the area.
Are tenants mostly:
Students?
Families?
Professionals?
Tourists?
International workers?
Temporary residents?
Different tenant groups create different rental patterns.
For example, a university market may have seasonal demand, while a business district may depend more heavily on employment conditions.
Prozameen’s Global Rental Market Trends 2026 provides broader insight into rental-market conditions.
Check Vacancy, Not Just Rent
A high advertised rent can look attractive.
But rental income only matters when the property is occupied.
Suppose one market offers higher rent but also higher vacancy.
Another market offers slightly lower rent but consistent occupancy.
The second market may produce better actual income.
Investors should therefore consider both:
Expected rent
and
Expected occupancy
A realistic rental analysis should include time between tenants, marketing periods and possible periods without income.
Use Prozameen’s Rental Yield Calculator to estimate rental performance using realistic income and expense assumptions.
Analyse Housing Supply
Supply is one of the most important—and often ignored—property-market indicators.
Strong demand can support prices and rents, but large amounts of new construction can change the market quickly.
Research:
Current housing inventory.
Projects under construction.
Approved future developments.
New infrastructure.
Available land.
Developer activity.
Imagine a neighbourhood where rents are currently strong.
If thousands of similar apartments are scheduled for completion over the next two years, tenants may soon have many more choices.
That can affect:
Rent growth.
Vacancy.
Resale competition.
Property prices.
The existing market and the future market may look very different.
Compare Supply With Demand
Supply should never be analysed alone.
A city can absorb large amounts of construction if its population and employment are also growing rapidly.
Likewise, a smaller amount of construction may still create oversupply in a stagnant area.
The important relationship is:
Housing supply relative to housing demand.
Ask whether new homes are being created faster than new households.
Also consider the type of supply.
A market may have enough housing overall but still suffer shortages in specific segments such as affordable apartments, family homes or centrally located rentals.
Study Population Trends
Real estate ultimately serves people.
Population trends therefore matter.
A growing population can support:
Housing demand.
Rental demand.
Retail activity.
Infrastructure investment.
But population growth needs deeper analysis.
Is the growth coming from long-term residents?
Students?
Temporary workers?
Retirees?
Migration?
Different demographic groups create different housing needs.
Also look at household formation.
Even if population growth is modest, demand can increase if average household size becomes smaller.
Employment Is a Major Demand Driver
People usually choose where to live based partly on where they can work.
A property market supported by diverse employment sectors may be more resilient than one dependent on a single employer or industry.
Research major employment sources such as finance, technology, manufacturing, tourism, healthcare, government, universities and logistics.
A market dependent heavily on one industry may face greater risk if that sector experiences a downturn.
Strong employment does not guarantee property growth, but it provides a useful foundation for long-term housing demand.
Look at Infrastructure Development
Infrastructure can influence property demand significantly.
New transport routes, airports, schools, hospitals, business districts and commercial centres may improve accessibility and attract residents.
But investors should separate:
Projects that are already funded or under construction
from
projects that are only proposed.
Property marketing often emphasizes future infrastructure.
Do not pay a premium based entirely on something that may be delayed, changed or cancelled.
The surrounding area should make sense as an investment even without optimistic future assumptions.
Evaluate the Location Within the Market
After evaluating the city or country, move to the neighbourhood level.
A strong national property market can contain weak areas.
Likewise, an average national market can contain excellent local neighbourhoods.
Look at transport, schools, employment access, shopping, healthcare, public spaces, safety, noise and nearby development.
Prozameen’s How to Choose the Right Property Location provides a structured way to evaluate local property locations.
Study Mortgage Conditions
Property markets are heavily influenced by credit.
When mortgage rates rise, monthly repayments increase.
That can reduce affordability and weaken buyer demand.
When financing becomes easier or cheaper, buyers may be able to afford higher property prices.
Investors should examine not only current mortgage rates but also lending conditions.
Are banks tightening lending?
Are larger deposits required?
Are borrowers qualifying easily?
Is mortgage demand increasing or decreasing?
For wider context, Prozameen’s Mortgage Rates & Housing Demand Report 2026 explores the relationship between financing and housing demand.
Calculate Rental Yield Carefully
Rental yield helps investors compare rental income with property value.
Suppose a property costs 300,000 and generates 18,000 in annual rent.
The simple gross rental yield would be:
18,000 ÷ 300,000 × 100 = 6%
But that does not mean the investor earns 6%.
Expenses may include maintenance, insurance, management, service charges, taxes and vacancy.
That is why investors should also understand Net Operating Income (NOI).
Compare Cap Rate and Cash Flow
Rental yield is useful, but it should not be the only measure.
Another important metric is Capitalization Rate (Cap Rate).
Cap rate compares Net Operating Income with property value.
For financed properties, investors may also want to examine cash-on-cash return because financing changes the actual amount of cash invested.
Using several measures produces a more realistic picture than relying on one headline percentage.
Study Property Taxes and Transaction Costs
A market may appear affordable until transaction costs are included.
Depending on the jurisdiction, buyers may face:
Transfer taxes.
Registration fees.
Legal costs.
Mortgage fees.
Brokerage costs.
Property taxes.
Association fees.
These expenses can significantly change investment returns.
Prozameen’s Property Purchase Cost Planner can help organize the costs involved in a property purchase.
Look at Ownership Costs After Purchase
Investment analysis should continue beyond the purchase date.
Ongoing ownership costs may include maintenance, insurance, utilities, building charges, property tax, management and repairs.
A property that appears attractive based on purchase price and rent can become much less attractive once recurring expenses are included.
Use the Property Ownership Cost Planner to estimate those continuing expenses.
Evaluate Market Liquidity
Property is less liquid than many financial investments.
Selling can take weeks or months.
Market liquidity tells you how easy it may be to find another buyer.
Useful indicators include:
Time properties remain on the market.
Number of active listings.
Number of transactions.
Price reductions.
Difference between asking prices and final sale prices.
A market where properties sell quickly and consistently may provide better exit flexibility than one where listings remain unsold for long periods.
Understand Who Will Buy From You Later
A useful investment question is:
Who is the future buyer?
Possible buyers may include local families, first-time buyers, investors, retirees or international purchasers.
A property that appeals to several buyer groups may be easier to sell than a highly specialized property.
This matters especially in markets dominated by investor purchases.
If most owners eventually try to sell to other investors, resale demand can weaken quickly when investment sentiment changes.
Compare Similar Properties
Market-level research tells you whether an area deserves attention.
The next step is property-level comparison.
Compare several properties based on:
Price.
Size.
Rent.
Operating expenses.
Condition.
Location.
Building quality.
Financing.
Potential resale demand.
Prozameen’s Property Comparison Tool can help structure this process.
Do Not Rely on One Metric
A common beginner mistake is choosing a property market because of one attractive number.
Examples include:
“Prices increased 15%.”
“Rental yield is 8%.”
“Population is growing.”
“Thousands of people are moving there.”
Each statistic can be useful.
But none should be used alone.
A stronger market evaluation combines:
Prices.
Income.
Rent.
Supply.
Demand.
Financing.
Employment.
Population.
Regulation.
Taxes.
Liquidity.
Risk.
The purpose is to understand the complete market rather than search for one number that confirms what you already want to believe.
Use Conservative Assumptions
Property investment forecasts often look attractive because the assumptions are optimistic.
A better approach is to stress-test the market.
Ask what happens if:
Rent is lower than expected.
The property remains vacant.
Mortgage costs increase.
Property prices remain flat.
Maintenance costs rise.
Resale takes longer.
If an investment only works under perfect conditions, it may carry more risk than it first appears.
Prozameen’s Property Deal Analyzer can help combine several property assumptions in one analysis.
Conduct Property-Level Due Diligence
Even after identifying a strong market, the individual property still needs to be verified.
Check ownership, title, building condition, outstanding debt, service charges, tenancy, approvals and restrictions.
A strong property market does not protect investors from buying a problematic property.
Use Prozameen’s Property Due Diligence Guide before making a purchase commitment.
Country, City, Neighbourhood, Property
A useful real estate research process moves from broad to specific.
Start with the country.
Then evaluate the city.
Then examine the neighbourhood.
Then study the building.
Finally, analyse the individual property.
This approach prevents investors from buying a poor property simply because they like the overall market story.
The article Best Countries to Invest in Real Estate 2026 can help with the first stage of international market comparison.
A Practical Market Evaluation Framework
Before investing, try to answer five questions.
Is demand real?
Are people actually moving, working, buying and renting in the area?
Is supply controlled?
Or are large numbers of competing properties coming?
Are prices supported by fundamentals?
Compare prices with rent, income and affordability.
Can the investment generate acceptable cash flow?
Calculate realistic rent and complete expenses.
Can you exit later?
Understand resale demand and liquidity.
If you cannot answer these questions clearly, more research may be necessary.
Common Property Market Warning Signs
Be cautious when a market depends heavily on aggressive marketing rather than measurable fundamentals.
Warning signs may include widespread guaranteed-return claims, rapidly increasing construction, weak local affordability, falling rents, rising vacancy, speculative buying and large differences between asking prices and actual transaction values.
None of these factors automatically means a market will perform poorly.
But several warning signs appearing together should encourage deeper investigation.
Key Takeaways
Evaluating a property market before investing means understanding far more than whether prices are currently rising.
A strong research process examines property prices, rental demand, housing supply, affordability, mortgage conditions, population, employment, infrastructure, taxes, ownership costs and resale liquidity.
The most important principle is simple:
Do not start with the property. Start with the market.
Then move from country to city, from city to neighbourhood and from neighbourhood to individual property.
Use realistic assumptions, compare several alternatives and complete proper due diligence before committing capital.
A disciplined market analysis cannot remove investment risk, but it can help you identify risks before they become expensive mistakes.
Important Information
Prozameen provides independent real estate information, research, calculators, tools and educational resources.
This article is for general informational and educational purposes only.
Property markets, regulations, taxes, financing conditions and investment risks vary by location and can change over time. Investors should independently verify information and obtain appropriate professional advice where necessary.