How to Start Investing in Real Estate With Low Capital
Real estate is often associated with large down payments, expensive properties and long-term mortgages, which can make it feel inaccessible to people with limited starting capital.
But buying an entire property is not the only way to gain exposure to real estate.
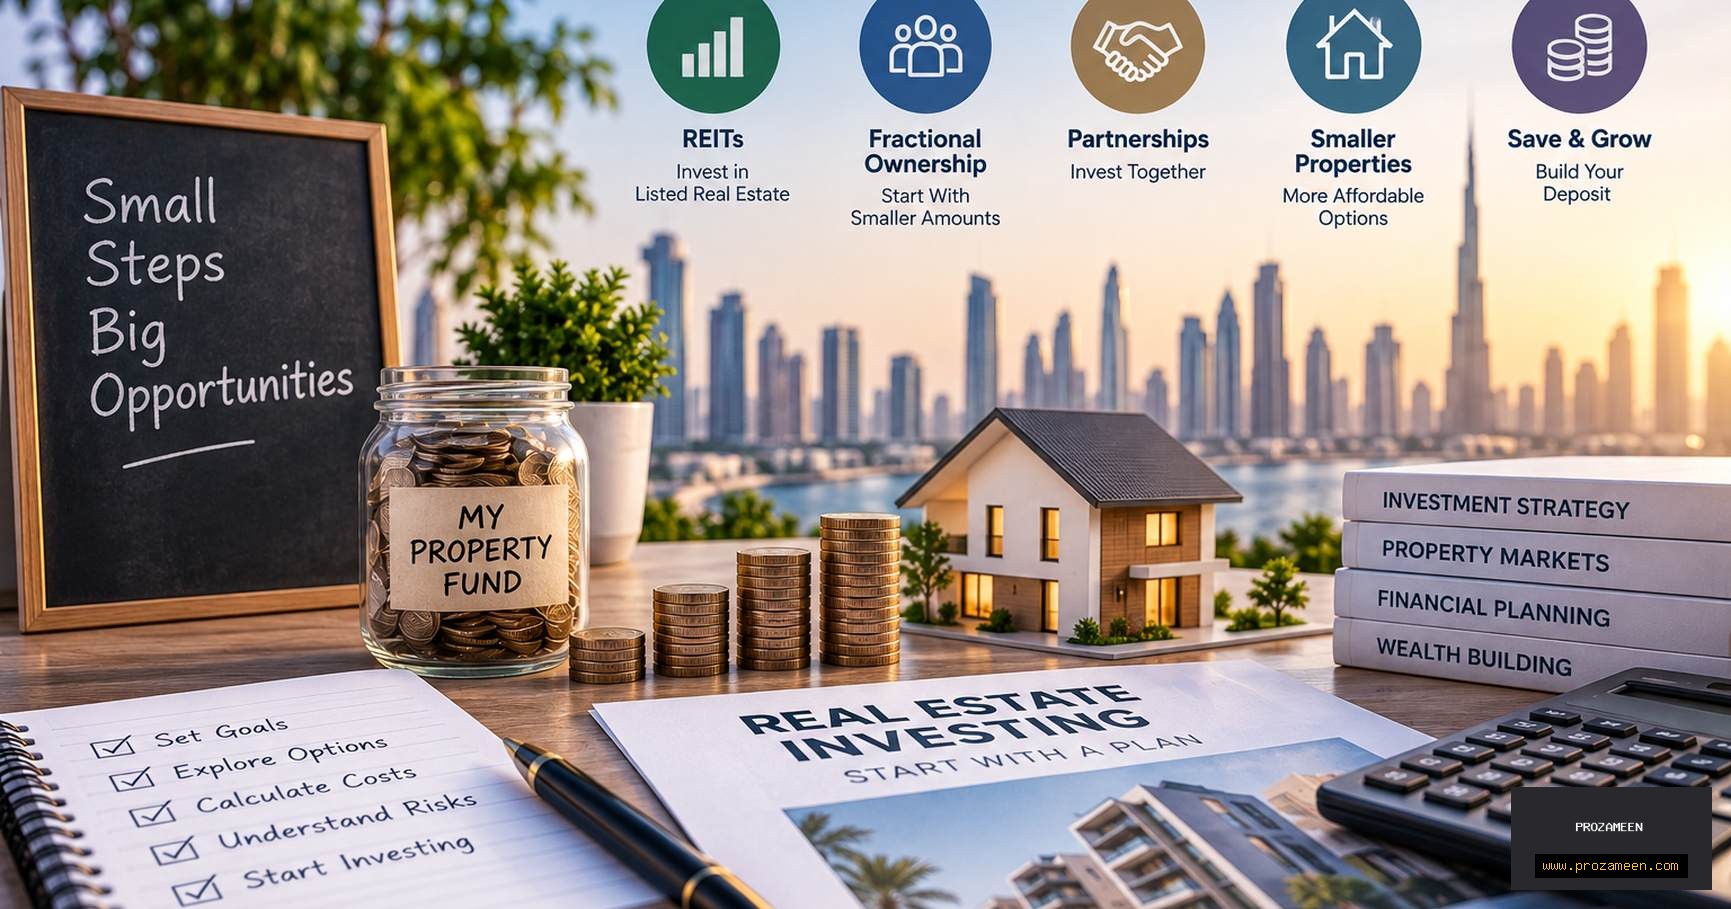
Depending on the country, regulations and investor profile, people may be able to start through listed real-estate investments, fractional ownership structures, partnerships, smaller properties or a gradual savings strategy aimed at future direct ownership.
The important point is not to search for the fastest way to “get into property.” A better approach is to understand how much capital you actually have, what level of risk you can accept, how liquid the investment is and what you legally own.
Start by Defining What “Low Capital” Means
Low capital means different things to different people.
Someone with 2,000 available to invest has very different options from someone with 20,000 or 50,000.
Before choosing an investment route, calculate:
- Available savings
- Emergency reserve
- Existing debt
- Monthly disposable income
- Expected investment period
- Need for liquidity
- Risk tolerance
You should avoid using money needed for rent, household expenses, emergencies or short-term commitments.
Real estate can be illiquid, especially when investing directly or through structures that do not allow easy resale.
Build an Emergency Reserve First
Before thinking about property returns, make sure unexpected expenses do not force you to sell an investment at the wrong time.
An emergency reserve can help cover:
- Job interruption
- Medical expenses
- Urgent household costs
- Unexpected debt payments
- Property expenses if you later become a landlord
The appropriate amount depends on personal circumstances, but the principle is simple:
Investment capital should be separate from emergency money.
Direct Property Ownership Requires More Than the Deposit
Beginners often focus only on the down payment.
But purchasing property can involve many additional costs.
These may include:
- Transfer or registration fees
- Legal costs
- Valuation fees
- Mortgage fees
- Property inspection
- Insurance
- Renovation
- Furnishing
- Initial maintenance
- Service charges
- Taxes
This means a property requiring a 10% or 20% down payment may still require significantly more cash than the deposit alone.
Use Prozameen's Property Purchase Cost Planner to estimate the broader upfront cost before setting a savings target.
Save Toward Direct Ownership Gradually
One of the most straightforward low-capital strategies is simply to build the required deposit over time.
This approach may feel slower, but it has several advantages.
It gives you time to:
- Improve savings
- Reduce existing debt
- Build credit history where relevant
- Research markets
- Understand financing
- Learn property analysis
Instead of rushing into a complex structure because it has a low entry amount, some investors may prefer to build capital gradually for direct ownership.
Start With Lower-Cost Property Markets
Property prices differ dramatically between countries, cities and neighbourhoods.
A deposit that is insufficient in one market may be meaningful in another.
However, investors should not choose a cheaper market solely because of price.
A low property price can sometimes reflect:
- Weak rental demand
- Limited employment
- Poor liquidity
- High vacancy
- Infrastructure problems
- Regulatory risk
- Declining population
The right question is not:
“Where is property cheapest?”
It is:
“Where does the combination of price, rental demand, costs and risk make sense?”
Smaller Properties May Require Less Capital
Smaller apartments, studios or modest residential units may have lower purchase prices than larger homes.
This can reduce the deposit requirement.
But smaller properties should still be analysed carefully.
Consider:
- Tenant demand
- Service charges
- Building condition
- Price per square metre
- Rental competition
- Resale demand
A cheaper unit is not automatically a better investment.
REITs as an Alternative to Direct Ownership
Real Estate Investment Trusts, commonly called REITs, can provide exposure to real estate without requiring investors to purchase an individual property.
REITs typically own or finance income-producing real estate.
Depending on the market, they may focus on:
- Residential property
- Offices
- Warehouses
- Shopping centres
- Healthcare property
- Hotels
- Data centres
Many REITs are publicly traded, making them easier to buy and sell than physical property.
Why REITs May Suit Lower-Capital Investors
Listed REITs can offer several potential advantages:
- Lower starting capital
- Easier diversification
- Greater liquidity
- No tenant management
- No direct renovation responsibility
- Professional property management
However, REIT prices can fluctuate with the stock market.
They can also be affected by interest rates, debt levels, property valuations and the performance of the underlying real estate sector.
Fractional Real Estate Investing
Some platforms allow multiple investors to participate in the economic ownership of a single property.
This is often described as fractional real estate.
Instead of buying the entire property, an investor commits a smaller amount and receives a proportional economic interest.
The exact legal structure varies.
Investors may own:
- Shares in a company that owns the property
- Units in a special-purpose vehicle
- Beneficial interests
- Another regulated structure
Understanding the legal structure is essential.
Questions to Ask Before Using a Fractional Platform
Before investing, investigate:
- Who legally owns the property?
- What exactly do I own?
- Is the platform regulated?
- What fees are charged?
- How is rental income distributed?
- Who manages the property?
- How can I exit?
- Is there a secondary market?
- What happens if the platform fails?
- How are taxes handled?
A low minimum investment does not mean the investment is low risk.
Liquidity Can Be Limited
One important difference between fractional property and listed shares is liquidity.
A platform may allow investors to buy into a property easily but make resale much harder.
Before committing money, understand whether you can exit:
- At any time
- Only after a fixed period
- Through another investor
- Only when the property is sold
Illiquidity is one of the most important risks beginners often overlook.
Real Estate Crowdfunding
Some jurisdictions allow real-estate crowdfunding.
Investors may contribute relatively small amounts to property projects, development loans or income-producing assets.
Crowdfunding structures can vary significantly.
An investment may involve:
- Equity ownership
- Debt investment
- Development finance
- Revenue participation
These structures carry different risks.
Development projects, for example, may involve construction delays, cost overruns or project failure.
Before investing, understand whether you are effectively acting as an owner, lender or another type of investor.
Property Partnerships
Two or more people may combine capital to purchase property together.
This can reduce the amount each person needs to contribute.
But partnerships create legal and practical complexity.
Before buying jointly, the partners should clearly agree on:
- Ownership percentages
- Initial contributions
- Mortgage responsibility
- Rental-income distribution
- Maintenance costs
- Decision-making
- What happens if someone wants to sell
- What happens if someone stops paying
- How disputes are resolved
These agreements should normally be documented properly rather than relying on informal verbal arrangements.
Family Partnerships Require the Same Discipline
Investing with relatives may feel simpler because trust already exists.
But financial disagreements can damage relationships.
Even between close family members, ownership structure and responsibilities should be documented clearly.
A professional legal agreement may help reduce future misunderstandings.
Mortgage Financing
A mortgage can allow buyers to purchase property with less than the full purchase price in cash.
However, borrowing should not be viewed as free capital.
Mortgage financing introduces:
- Interest cost
- Monthly repayment obligations
- Credit requirements
- Rate risk
- Refinancing risk
- Potential foreclosure risk
Higher leverage can increase both potential upside and downside.
Avoid Maximum Borrowing Just Because It Is Available
A lender approving a certain mortgage amount does not necessarily mean that amount is financially comfortable.
An investor should stress-test the purchase.
Ask:
- Can I afford payments if interest rates increase?
- What if the property is vacant?
- What if rent is lower than expected?
- What if repairs are needed?
- What if my personal income declines?
A conservative financing structure can provide more flexibility.
House Hacking
In some markets, an owner may purchase a property and rent out part of it while living in another part.
This concept is sometimes called house hacking.
Examples may include:
- Renting a spare room
- Living in one unit of a multi-unit building
- Renting a permitted accessory unit
This can help offset housing costs.
However, local rental laws, mortgage conditions, tax rules and property configuration should always be checked.
Renting Out a Room
For some homeowners, renting a room can be a lower-cost introduction to property income.
But rules differ by country and building type.
Owners should understand:
- Tenant rights
- Tax treatment
- Insurance
- Building association rules
- Safety requirements
- Contract terms
Never assume room rental is automatically unrestricted.
Off-Plan Property and Low Deposits
Some developers market off-plan properties using installment plans or relatively low initial deposits.
This can reduce the upfront cash requirement.
However, lower initial capital does not reduce project risk.
Potential risks include:
- Construction delays
- Developer failure
- Market decline before completion
- Payment obligations
- Changes in financing availability
- Oversupply
- Contract restrictions
Before purchasing off-plan property, verify the developer, project registration, payment structure and buyer protections.
Renovation Properties
Some investors look for lower-priced properties that need improvement.
A renovation strategy may create value, but it requires realistic budgeting.
Common risks include:
- Hidden structural problems
- Contractor delays
- Material-cost increases
- Permit issues
- Budget overruns
The purchase price should be considered together with the total renovation requirement.
Prozameen's Property Renovation Budget Planner can help organize estimated renovation costs.
Avoid “Cheap Property” Marketing
Properties marketed as low-cost opportunities can sometimes come with hidden problems.
Be cautious if a property is promoted mainly with phrases such as:
- “Guaranteed return”
- “Below-market opportunity”
- “Limited-time investment”
- “Instant equity”
- “Risk-free property”
- “Guaranteed appreciation”
The lower the price, the more important it becomes to understand why the property is inexpensive.
Start With Education Before Capital
If your starting capital is small, one of the highest-value investments may be improving your knowledge.
Learn how to calculate:
- Rental yield
- Net Operating Income
- Cash flow
- Cash-on-cash return
- Loan-to-value
- DSCR
- Purchase costs
- Holding costs
Understanding these concepts can help prevent expensive mistakes later.
Build a Property Research Process
Before investing, use the same research process for every opportunity.
Review:
- Local housing demand
- Property prices
- Rental income
- Vacancy
- Future supply
- Employment
- Transport
- Property condition
- Ownership rules
- Taxes
- Financing
Consistency helps reduce emotional decision-making.
Understand Gross vs Net Returns
A property may advertise an 8% gross yield.
That does not mean the investor earns 8%.
Operating expenses can include:
- Management
- Maintenance
- Insurance
- Property tax
- Service charges
- Vacancy
- Repairs
The net return may be much lower.
Always ask whether a quoted return is gross or net.
Cash Flow Matters
A property can look attractive on paper but create monthly financial pressure.
Cash flow considers both income and outgoing payments.
A simplified formula is:
Rental Income − Operating Costs − Debt Payments = Cash Flow
Positive cash flow is not guaranteed.
A property can also become cash-flow negative if interest rates rise or rent declines.
Build Capital Through Regular Saving
Investors sometimes focus heavily on finding a shortcut into property.
A more sustainable strategy can be systematic saving.
Regular monthly saving can increase:
- Deposit
- Emergency reserve
- Renovation budget
- Financing flexibility
It can also reduce the need for excessive borrowing.
Consider Diversified Real Estate Exposure
A person with limited capital may benefit from diversification more easily through listed real-estate funds than through purchasing one physical property.
One small direct property investment can concentrate risk heavily.
Diversified real-estate securities may spread exposure across multiple properties, sectors or regions.
However, financial-market volatility remains a risk.
Avoid Unregulated Schemes
Low-capital investors are often targeted by schemes promising easy property ownership or unusually high returns.
Before investing, check whether the platform, company or investment structure is regulated where required.
Be cautious if the provider:
- Avoids explaining ownership
- Promises guaranteed returns
- Prevents independent legal review
- Uses high-pressure sales tactics
- Cannot clearly explain fees
- Offers unclear exit terms
Think About Exit Before Entry
Before investing, understand how you can get your money back.
This is particularly important for:
- Fractional property
- Crowdfunding
- Private partnerships
- Off-plan investment
Ask:
Who will buy my interest if I want to exit?
If the answer is unclear, liquidity risk may be high.
A Practical Example
Imagine an investor has 15,000 available.
They may consider three broad paths.
Option 1: Save longer
Continue saving until there is enough capital for a direct property deposit and purchase costs.
Option 2: Listed real estate
Invest part of the money in a diversified listed REIT or real-estate fund.
Option 3: Fractional investment
Use a regulated platform to invest a smaller amount into a property structure.
Each option has different characteristics.
Saving provides flexibility but no immediate real-estate exposure.
Listed investments provide liquidity but market volatility.
Fractional property may provide direct real-estate exposure but lower liquidity.
There is no universal answer.
Common Beginner Mistakes
People starting with limited capital sometimes make mistakes because they feel pressure to enter the market quickly.
Common examples include:
- Investing emergency savings
- Borrowing excessively
- Ignoring transaction costs
- Choosing unregulated platforms
- Believing guaranteed-return claims
- Focusing only on gross yield
- Ignoring liquidity
- Buying in unfamiliar overseas markets
- Failing to understand ownership structure
Low starting capital makes careful risk management even more important.
A Better Low-Capital Strategy
A sensible approach may involve several stages.
Stage 1 — Financial foundation
Build emergency savings and reduce expensive debt.
Stage 2 — Education
Learn real-estate metrics and local regulations.
Stage 3 — Capital building
Save regularly while researching markets.
Stage 4 — Small exposure
Consider diversified listed real-estate investment where appropriate.
Stage 5 — Direct ownership
Move toward physical property only when the capital, financing and risk profile are manageable.
This gradual approach can be more sustainable than rushing into the first available opportunity.
Prozameen Resources That Can Help
Prozameen provides educational tools that can support beginner research, including:
- Down Payment Calculator
- Mortgage / EMI Calculator
- Property Purchase Cost Planner
- Rental Yield Calculator
- ROI Calculator
- Cash-on-Cash Return Calculator
- LTV Calculator
- Property Comparison Tool
- Property Due Diligence Guide
- Rental Property Investment Guide for Beginners
These tools are designed to help users understand property economics rather than recommend a specific investment.
Key Takeaways
Starting with limited capital does not mean real-estate investing is impossible.
But it does mean investors need to be especially careful about structure, fees, liquidity and risk.
Direct ownership may require time to build sufficient savings.
REITs and listed property funds can offer lower-cost access to real-estate exposure.
Fractional property and crowdfunding may reduce entry costs but can introduce liquidity and platform risk.
Partnerships may allow capital to be combined, but legal agreements become important.
The strongest starting point is usually not finding the cheapest investment.
It is building financial stability, knowledge and a repeatable research process.
Important Information
Prozameen provides independent real-estate information, research, calculators and educational resources.
This article is provided for general informational and educational purposes only.
Investment products, property laws and financing rules vary by jurisdiction. Readers should independently verify applicable rules and obtain professional advice where necessary.