Best Property Investment Strategies for Beginners 2026
Starting a property investment journey can feel complicated because there are many different strategies, markets and financial terms to understand.
Some investors focus on long-term rental income. Others look for properties they can renovate, buy before completion, hold for appreciation or access indirectly through listed real-estate investments.
For beginners, the most important step is not finding the strategy that promises the highest return. It is understanding how each strategy works, how much capital it requires, what risks it creates and whether it matches your financial situation and investment timeframe.
A sensible property strategy should be based on research, realistic numbers and manageable risk rather than market hype.
Start With Your Investment Goal
Before comparing properties, decide what you actually want the investment to achieve.
Common objectives include:
- Generating recurring rental income
- Building long-term property ownership
- Diversifying existing investments
- Preserving capital over a long period
- Renovating and improving property
- Combining rental income with potential appreciation
Different goals can lead to very different property choices.
An investor looking for stable rental income may prefer an established residential area with consistent tenant demand, while someone focusing on renovation may accept a property requiring substantial work.
There is no single strategy that fits every investor.
Strategy 1: Long-Term Rental Property
Long-term rental property is one of the most familiar real-estate investment strategies.
The investor purchases a property and rents it to tenants, usually under a longer residential lease.
Income may come from:
Rental income
and potentially:
Changes in property value over time
However, neither is guaranteed.
Before purchasing a rental property, estimate:
- Purchase price
- Expected rent
- Vacancy
- Maintenance
- Insurance
- Service charges
- Property taxes
- Management fees
- Financing costs
Use Prozameen’s Rental Yield Calculator to compare expected rental income with property value and annual expenses.
Gross Rent Is Not Profit
A beginner may see a property renting for 2,000 per month and assume annual income will be 24,000.
But property ownership may also involve substantial expenses.
For example:
Annual Rent: 24,000
Less:
- Maintenance
- Insurance
- Property management
- Vacancy
- Service charges
- Local taxes
The amount remaining may be significantly lower.
This is why investors should understand Net Operating Income (NOI) rather than focusing only on gross rent.
Strategy 2: Buy-and-Hold Property
A buy-and-hold strategy involves purchasing property with the intention of owning it for several years rather than selling quickly.
The investment thesis may involve:
- Rental income
- Mortgage repayment
- Long-term market exposure
- Potential appreciation
This strategy can reduce the importance of short-term price movements, but it does not eliminate risk.
Long-term owners still need to consider:
- Property maintenance
- Financing
- Changes in tenant demand
- Local housing supply
- Regulation
- Market cycles
The Property Ownership Cost Planner can help organize recurring ownership expenses that may affect long-term holding performance.
Strategy 3: Value-Add Property
A value-add strategy involves purchasing a property that may improve through renovation, better management or physical upgrades.
Examples include:
- Updating an outdated kitchen
- Renovating bathrooms
- Improving energy efficiency
- Repairing neglected interiors
- Improving landscaping
- Modernizing fixtures
The objective is not simply to spend money on renovation.
The improvements should ideally increase usability, rental appeal, marketability or property value.
Renovation Risk
Renovation can create opportunities, but it can also create unexpected costs.
Common risks include:
- Structural issues
- Plumbing problems
- Electrical work
- Permit requirements
- Contractor delays
- Material-price increases
- Budget overruns
Before purchasing a property that requires significant work, use the Property Renovation Budget Planner to estimate repair and improvement costs.
A contingency budget is also important because renovation rarely follows the original estimate perfectly.
Strategy 4: Off-Plan Property
Off-plan property is purchased before construction is completed.
In some markets, buyers may pay through staged payment plans rather than paying the entire amount immediately.
Potential considerations include:
- Lower initial payment
- New construction
- Modern facilities
- Developer payment plans
But off-plan investing also introduces important risks.
These can include:
- Construction delays
- Developer risk
- Market changes before completion
- Payment obligations
- Oversupply
- Resale restrictions
- Changes in financing availability
Beginners should verify the developer, project registration, escrow protections where applicable and the legal terms of the purchase agreement.
Never rely only on marketing material.
Strategy 5: Smaller Residential Properties
Some beginners start by researching smaller apartments, studios or modest residential units because they may require less total capital than larger homes.
Potential advantages can include:
- Lower purchase price
- Smaller deposit requirement
- Broader tenant affordability
- Lower furnishing costs
But smaller property is not automatically safer.
Research:
- Price per square metre
- Service charges
- Tenant demand
- Resale demand
- Building quality
- Future supply
Use the Property Comparison Tool to compare multiple properties using consistent financial criteria.
Strategy 6: REITs and Listed Real Estate
Direct property ownership is not the only way to invest in real estate.
Real Estate Investment Trusts and listed property companies can provide exposure to income-producing property through financial markets.
Depending on the investment, underlying assets may include:
- Apartments
- Offices
- Warehouses
- Shopping centres
- Hotels
- Healthcare buildings
- Data centres
Potential advantages include:
- Lower entry capital
- Greater liquidity
- Professional management
- Diversification across multiple properties
However, publicly traded real-estate investments can fluctuate like other financial securities.
Their value can be affected by:
- Interest rates
- Property values
- Debt
- Market sentiment
- Sector performance
Investors should therefore understand that REITs are real-estate investments but behave differently from owning a physical rental property directly.
Strategy 7: Fractional Real Estate
Fractional real-estate platforms may allow several investors to participate in one property using smaller individual contributions.
This can reduce the amount needed to obtain property exposure.
However, the investment structure matters enormously.
Before investing, ask:
- What exactly do I legally own?
- Who owns the property?
- Who manages it?
- Is the platform regulated?
- What fees apply?
- How is rental income distributed?
- Can I sell my interest?
- What happens if the platform fails?
Limited liquidity can be an important risk.
The ability to invest quickly does not always mean you can exit quickly.
Strategy 8: Property Partnerships
Some investors combine capital with another person or several partners to purchase property.
This can reduce the amount each individual needs to contribute.
But partnerships require clear agreements.
Important topics include:
- Ownership percentages
- Mortgage obligations
- Rental-income distribution
- Maintenance responsibility
- Decision-making authority
- Future capital contributions
- Exit arrangements
Even when investing with relatives or close friends, written legal agreements are preferable to informal understandings.
Strategy 9: Short-Term Rental Property
Short-term rental property can generate income from guests rather than long-term tenants.
Potential demand may come from:
- Tourism
- Business travel
- Events
- Seasonal visitors
- Temporary relocation
However, short-term rental income can be more operationally intensive.
Expenses may include:
- Furnishing
- Cleaning
- Utilities
- Booking-platform fees
- Property management
- Guest communication
- Licensing
Occupancy can also vary significantly between seasons.
Local laws and building regulations should be checked before assuming that short-term rental activity is permitted.
Long-Term Rental vs Short-Term Rental
Neither model is universally superior.
Long-term rentals may provide more predictable tenancy but potentially lower flexibility.
Short-term rentals may offer different revenue opportunities but require more active management.
Compare both using:
- Expected annual income
- Vacancy
- Operating expenses
- Management
- Regulation
- Tenant or guest turnover
The best approach depends on the property and market.
Strategy 10: Investing for Rental Yield
Some investors focus primarily on rental yield.
A simplified gross rental yield formula is:
Annual Rental Income ÷ Property Value × 100
For example:
Property value: 250,000
Annual rent: 15,000
Gross rental yield:
15,000 ÷ 250,000 × 100 = 6%
But gross yield does not include every operating expense.
For a deeper explanation, read What Is a Good Rental Yield for a Property?.
Strategy 11: Investing Using Cap Rate
Capitalization Rate, or Cap Rate, compares property operating income with property value.
The simplified formula is:
Cap Rate = NOI ÷ Property Value × 100
Cap rate can help compare income-producing properties without directly including the investor's individual financing structure.
Learn more in Prozameen’s Capitalization Rate (Cap Rate) glossary or use the Cap Rate Calculator.
Strategy 12: Cash-on-Cash Focus
Cash-on-cash return compares annual cash flow with the investor's actual cash invested.
It can be particularly useful when financing is involved.
For example, two properties may have similar values but very different investor cash requirements because of differences in:
- Down payment
- Renovation
- Financing
- Purchase costs
Learn more about Cash-on-Cash Return or test assumptions with the Cash-on-Cash Return Calculator.
Financing Strategy Matters
The same property can produce very different investor results depending on how it is financed.
Important considerations include:
- Down payment
- Mortgage interest rate
- Loan term
- Monthly repayment
- Variable or fixed interest
- Loan-to-value
Use the Mortgage / EMI Calculator to estimate loan payments and the Loan-to-Value (LTV) Calculator to understand leverage.
Avoid Excessive Leverage
Borrowing can allow investors to control a larger asset using less personal capital.
But leverage magnifies risk as well as exposure.
If rent falls or interest rates rise, mortgage payments still need to be made.
A beginner should therefore avoid assuming that the maximum loan offered by a lender is automatically the correct amount to borrow.
Stress-test the investment using less favourable assumptions.
Understand DSCR
Debt Service Coverage Ratio measures whether property operating income is sufficient to cover debt payments.
A simplified formula is:
DSCR = Net Operating Income ÷ Annual Debt Payments
A DSCR below 1 indicates that operating income alone is insufficient to cover debt payments.
Use Prozameen’s DSCR Calculator when evaluating income-producing property with financing.
Location Is Part of the Strategy
A property strategy cannot be separated from location.
Important location factors include:
- Employment
- Population
- Transport
- Schools
- Universities
- Infrastructure
- New housing supply
- Local amenities
A strategy that works in one neighbourhood may perform poorly in another.
Read How to Choose the Right Property Location before comparing markets.
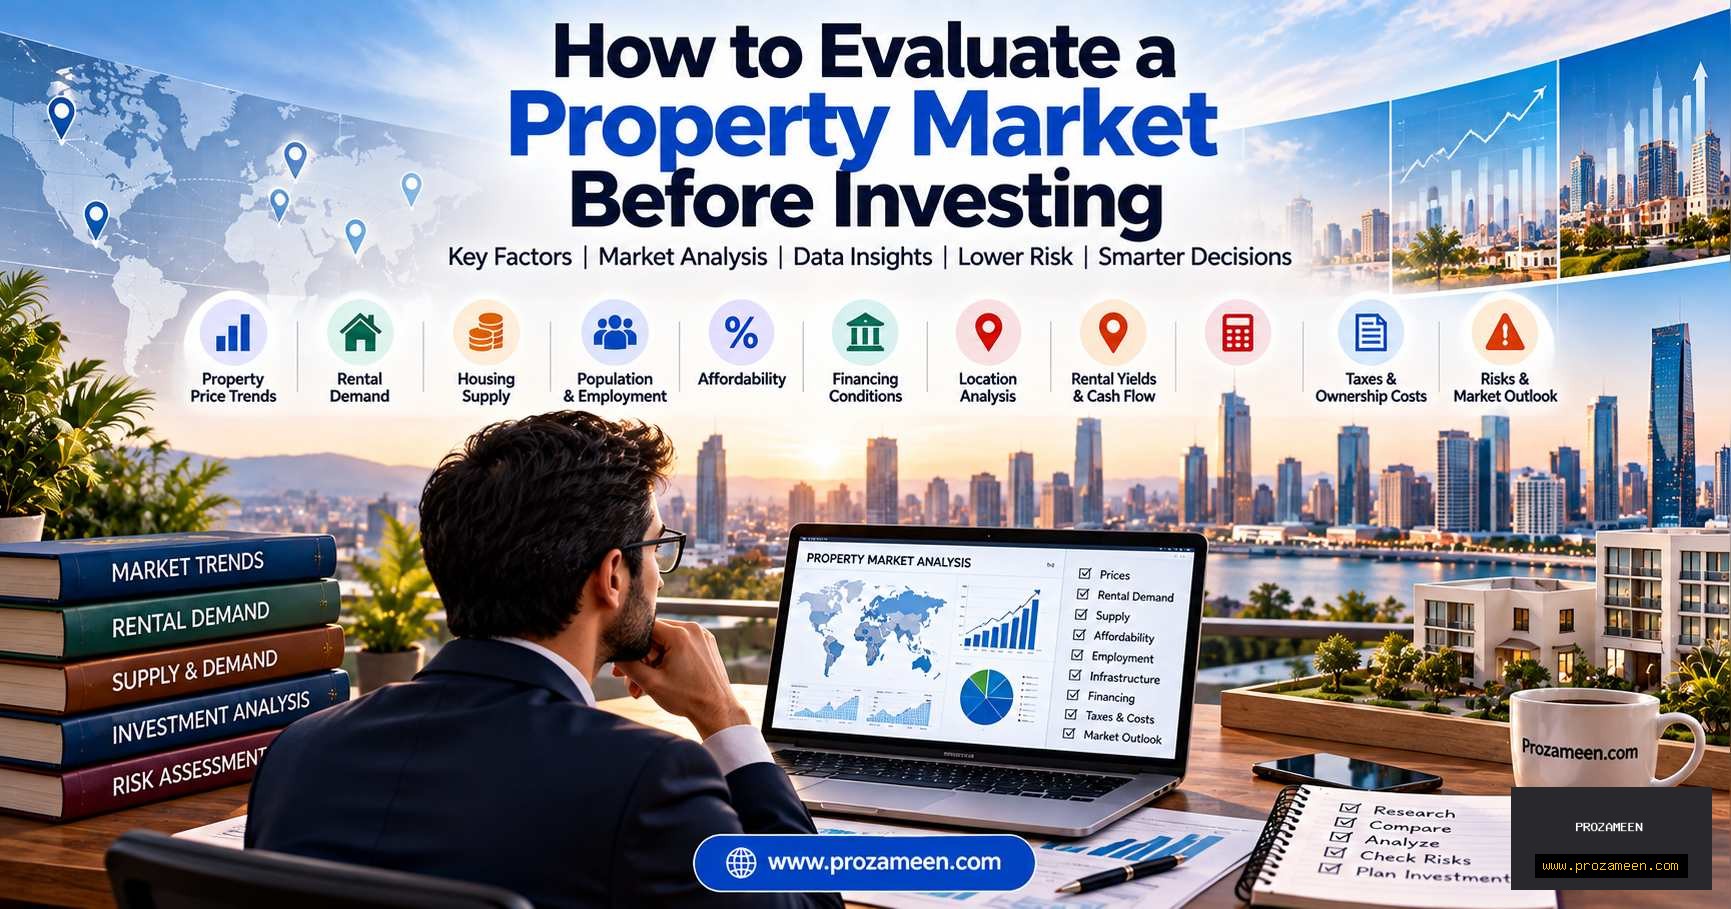
Research the Property Price
Do not assume that a property is good value simply because it is located in a popular market.
Compare:
- Recent transactions
- Price per square metre
- Property condition
- Building quality
- Comparable properties
The Property Valuation Guide for Buyers & Investors explains several ways buyers and investors can evaluate property value.
Understand Market Conditions
Property markets can move differently even within the same country.
Some areas may experience strong housing demand while others have excess inventory.
Before buying, look at:
- Recent price trends
- Rental trends
- Inventory
- Construction
- Mortgage conditions
- Local economic activity
For broader market context, Prozameen’s Global Real Estate Market Outlook 2026 explores major housing, investment and financing trends.
Property Prices Do Not Always Rise
Beginners should avoid strategies based entirely on future appreciation.
Property prices can:
- Rise
- Remain flat
- Decline
Future values depend on interest rates, supply, demand, employment, economic conditions and local circumstances.
The Global Property Price Trends Report 2026 provides broader context on differences between international housing markets.
Rental Markets Also Change
Rental demand is not permanent.
Employment shifts, construction and population changes can alter tenant demand.
Before relying on rental income, research the local rental market and future housing pipeline.
For wider context, see Prozameen’s Global Rental Market Trends 2026.
Do Not Ignore Purchase Costs
The property price is only part of the required investment.
Potential acquisition expenses may include:
- Registration
- Transfer taxes
- Legal costs
- Mortgage fees
- Inspection
- Renovation
- Furnishing
Use the Property Purchase Cost Planner before deciding how much capital is available for a purchase.
Build a Maintenance Reserve
Property ownership can produce unexpected expenses.
A reserve can help cover:
- Repairs
- Vacancy
- Insurance deductibles
- Appliance replacement
- Building maintenance
An investment that only works financially when nothing goes wrong may be too fragile.
Due Diligence Is Part of Every Strategy
Regardless of strategy, due diligence should be completed before purchase.
Review:
- Legal ownership
- Property documents
- Physical condition
- Existing tenancy
- Service charges
- Building finances
- Development approvals
- Restrictions
Use the Property Due Diligence Guide for a structured overview of these checks.
Inspect the Property
A physical inspection can reveal issues that are not obvious from online photographs.
The Property Viewing Checklist can help organize what to examine during a viewing.
For rental investments, also use the Rental Property Inspection Checklist.
Compare Several Properties
Beginners sometimes become emotionally attached to the first property that appears attractive.
Instead, compare several options using consistent criteria.
Evaluate:
- Price
- Rent
- Expenses
- Location
- Condition
- Financing
- Yield
- Resale demand
The Property Comparison Tool can help structure this analysis.
Use Multiple Investment Metrics
Do not make a decision using only one number.
A stronger analysis may include:
Rental Yield
Measures rent relative to property value.
NOI
Measures operating income after operating expenses.
Cap Rate
Compares NOI with property value.
Cash-on-Cash Return
Compares annual cash flow with invested cash.
DSCR
Measures debt coverage.
ROI
Provides a broader view of return relative to investment.
Prozameen’s Property Deal Analyzer can help bring several of these concepts together.
Which Strategy Is Suitable for Beginners?
There is no universal answer.
A beginner with limited capital, limited property-management experience and a strong need for liquidity may view real estate differently from someone with significant savings and experience managing rental property.
Rather than searching for the “best” strategy, compare:
- Capital required
- Expected income
- Management requirements
- Financing
- Liquidity
- Market risk
- Legal complexity
- Time horizon
The strategy should fit the investor rather than forcing the investor to fit the strategy.
Common Beginner Mistakes
Some common mistakes include:
- Buying based on emotion
- Believing guaranteed-return claims
- Ignoring ownership costs
- Borrowing too aggressively
- Assuming full occupancy
- Ignoring future supply
- Skipping inspections
- Failing to verify ownership
- Using unrealistic rental assumptions
- Relying on appreciation forecasts
Avoiding these mistakes can be more important than choosing a supposedly sophisticated investment strategy.
A Practical Beginner Process
A simple process can be:
Step 1 — Define your goal
Income, long-term ownership, diversification or another objective.
Step 2 — Set a realistic budget
Include deposit, purchase costs and emergency reserves.
Step 3 — Research locations
Understand supply, demand and local economics.
Step 4 — Compare several properties
Avoid deciding from one listing.
Step 5 — Analyse income and expenses
Calculate yield, NOI and cash flow.
Step 6 — Stress-test financing
Consider higher rates and vacancy.
Step 7 — Complete due diligence
Verify documents and property condition.
Step 8 — Plan the exit
Know how the investment may eventually be sold.
Key Takeaways
Property investment offers several possible strategies, but beginners should avoid approaching real estate as a shortcut to wealth.
Long-term rentals, value-add property, off-plan purchases, REITs, fractional real estate and other strategies all have different capital requirements and risks.
The strongest strategy is usually the one that can be understood, financed responsibly and evaluated using realistic numbers.
For beginners, the priorities should be:
Research the market.
Understand the property.
Calculate complete costs.
Use manageable financing.
Diversify where practical.
Complete due diligence.
Never rely on guaranteed-return claims.
A disciplined research process is more valuable than chasing whichever property strategy happens to be most popular at the moment.
Important Information
Prozameen provides independent real-estate information, research, calculators, tools and educational resources.
This article is provided for general informational and educational purposes only and does not constitute personalized investment, financial, legal, mortgage, tax, valuation or property advice.
Property markets, regulations, taxes, financing conditions and investment risks vary by country and can change over time. Readers should independently verify information and obtain appropriate professional advice where necessary.