
Rent vs Buy Market Report 2026
Should you rent or buy a home in 2026?
It sounds like a simple question, but current housing data shows why there is no universal answer.
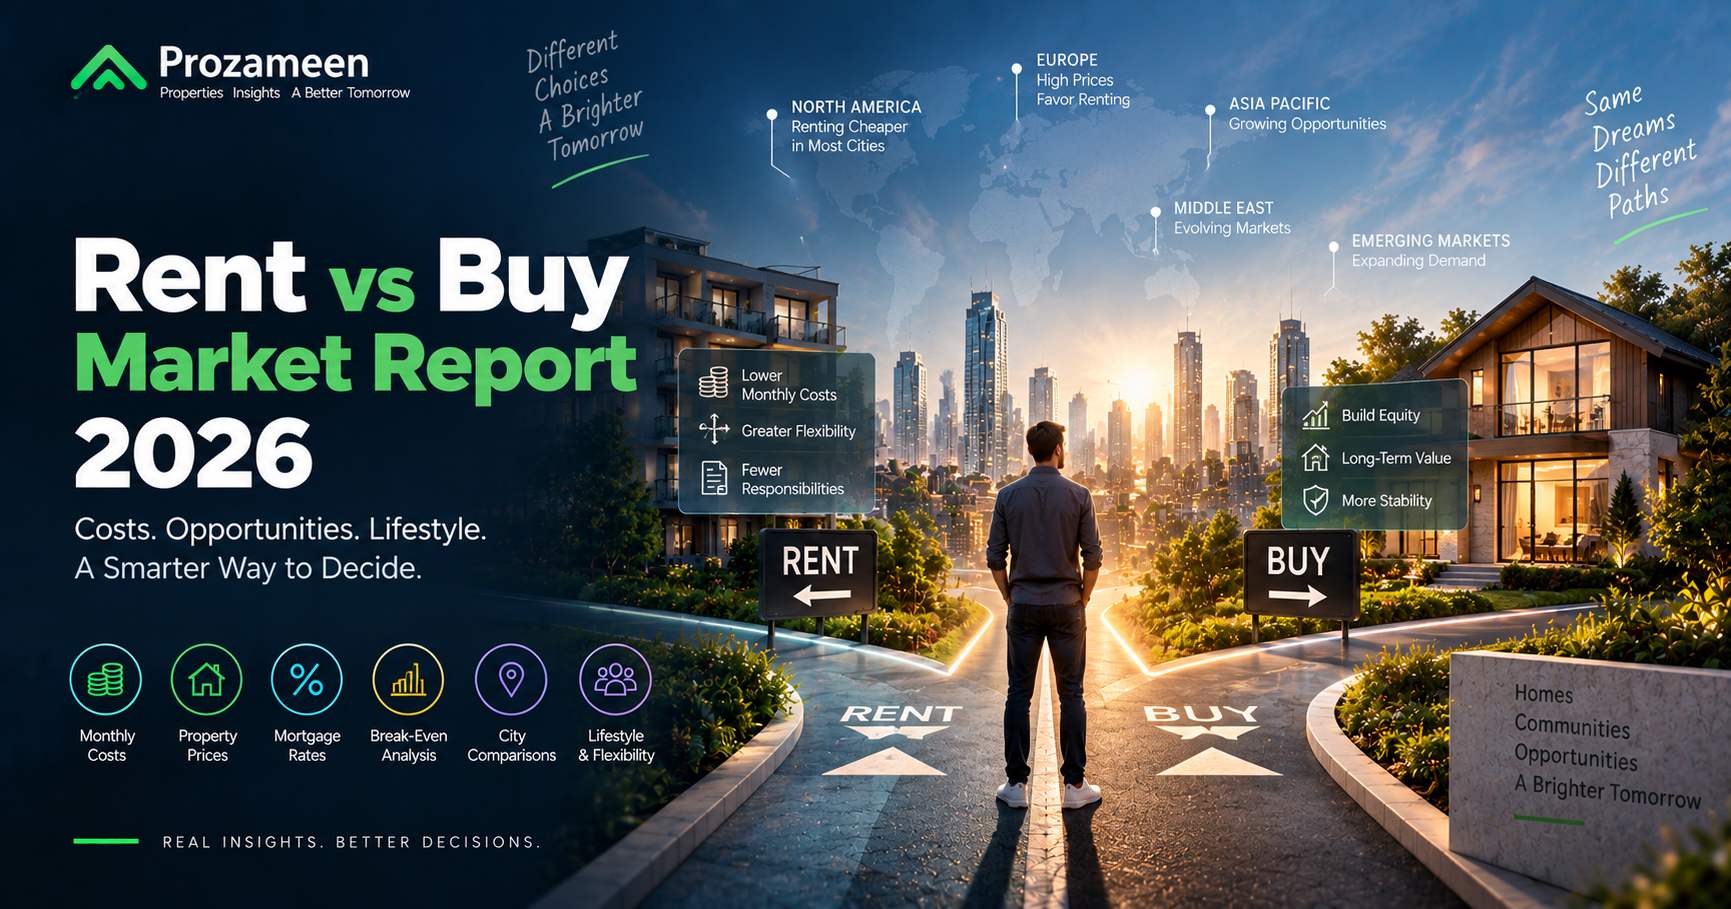
In many major markets, renting currently requires a lower monthly housing payment than buying. At the same time, buyers who remain in a property long enough may gradually build equity and recover the higher upfront and ownership costs.
The Prozameen Rent vs Buy Market Report 2026 examines how property prices, rents, mortgage rates, down payments, ownership costs and expected length of stay are shaping this decision.
Executive Summary
Several important trends define the rent-versus-buy market in 2026:
- Renting currently has a significant monthly cost advantage in many major U.S. markets
- The financial advantage of buying can improve over longer ownership periods
- Mortgage rates remain an important affordability barrier
- European house prices have generally been rising faster than rents
- Renting is currently more affordable than buying in many major European cities
- Down payments and transaction costs remain major barriers to ownership
- Location dramatically changes the calculation
- A short expected stay generally strengthens the case for renting
- Longer ownership periods can improve the economics of buying
- Monthly cost alone does not determine the better financial outcome
The central lesson is that rent versus buy should be treated as a time-horizon and affordability calculation rather than a universal rule.
Renting Has a Monthly Cost Advantage in the U.S.
The clearest current evidence comes from the United States.
Zillow reported in September 2026 that the typical U.S. renter paid approximately $1,948 per month in August, compared with approximately $3,014 per month for the typical new buyer's mortgage payment, property taxes and insurance.
That represented a monthly difference of about $1,066, or nearly $12,800 per year. Zillow found renting was less expensive on a monthly basis across all 50 of the largest U.S. metropolitan areas.
This does not mean renting will always produce the better long-term financial result.
It means that the immediate cash-flow requirement for a new buyer is currently substantially higher in many markets.
The Gap Can Be Much Larger in Expensive Cities
The monthly difference between renting and buying varies dramatically by location.
Zillow's August 2026 analysis estimated particularly large monthly rental advantages in expensive coastal markets, including:
- San Jose
- San Francisco
- Los Angeles
- San Diego
In San Jose, Zillow estimated that renting the typical home cost approximately $7,883 less per month than the monthly cost faced by a typical new buyer under its methodology.
This illustrates why national averages should never replace local research.
Monthly Cost Is Only Part of the Story
A lower monthly rent does not automatically mean renting produces the best long-term financial outcome.
Homeowners gradually repay mortgage principal and may build equity.
Renters do not build property equity, but they may retain money that would otherwise have been used for:
- Down payment
- Closing costs
- Higher monthly payments
- Property maintenance
- Repairs
If renters save or invest those differences, the financial comparison changes significantly.
A proper rent-versus-buy analysis therefore needs to compare wealth accumulated under both scenarios, not simply rent versus mortgage payments.
Buying Can Become More Competitive Over Time
Zillow's June 2026 rent-versus-buy model estimated that a purchaser of the typical U.S. home would financially break even compared with renting after approximately 5.9 years with a 5% down payment and around 6.0 years with 20% down, based on the assumptions used in its model.
This helps explain an apparent contradiction in the market:
Renting may be substantially cheaper today, while buying may become financially competitive after several years.
The expected length of stay is therefore one of the most important factors in the decision.
The Break-Even Period Varies by City
There is no universal number of years that makes buying better.
Zillow estimated that buy-versus-rent break-even could arrive within roughly 3.5 to 4.2 years in markets such as Columbus, Memphis and Buffalo, depending on down payment assumptions.
At the opposite end, its model found that current prices and rents in San Francisco, San Jose and New Orleans left renting ahead even across a 30-year modelling horizon.
The differences reflect local combinations of:
- Property prices
- Rents
- Property taxes
- Insurance
- Expected appreciation
- Transaction costs
- Mortgage costs
U.S. Buyers Still Face High Financing Costs
The cost of financing continues to affect the rent-versus-buy calculation.
Zillow reported in its August 2026 housing-market update that mortgage rates remained above 6.5%, while the typical U.S. home value was approximately $369,678.
The report described renting as the more affordable current option for many households because borrowing costs remain elevated.
Higher interest rates increase the monthly payment without increasing the amount of property the buyer owns.
Renting Also Has Costs That Can Change
Renting is not financially static.
Rents can increase, and households may face:
- Security deposits
- Moving expenses
- Parking costs
- Utility charges
- Rent increases at renewal
- Repeated relocation costs
Zillow reported that typical U.S. rent reached $1,948 in August 2026, approximately 2.5% higher than one year earlier.
This means today's rental advantage may change over time.
Rental Concessions Can Lower the Effective Rent
Headline asking rent may also overstate what a renter effectively pays.
In July 2026, Zillow reported that 39.8% of U.S. rental listings offered some form of concession, such as free rent, waived fees or other incentives.
Renters comparing costs should therefore investigate the effective rental cost rather than relying only on the advertised monthly price.
Europe Shows a Similar Affordability Challenge
The rent-versus-buy question is also important across Europe.
JLL reported that in the second quarter of 2026, renting was more affordable than buying in approximately two-thirds of the key European cities included in its analysis, largely because of high property prices and mortgage costs.
However, renting is not becoming cheaper everywhere.
The same JLL analysis showed average residential rents across its European city sample increasing around 3.4%, slightly faster than residential sales prices at 3.1% in Q2 2026.
EU House Prices Are Rising Faster Than Rents
Eurostat provides a broader view of European housing trends.
In the first quarter of 2026, EU house prices increased 5.1% year over year, while rents increased 3.0%.
Compared with the previous quarter, house prices increased 1.2% and rents 0.7%.
When purchase prices grow faster than rents, buying can become relatively more expensive for new entrants even if existing homeowners benefit from rising property values.
Mortgage Costs Still Matter in Europe
Financing remains important in European affordability.
The European Central Bank reported that the composite cost of borrowing for euro-area household home purchases was approximately 3.54% in July 2026.
The ECB also reported that euro-area banks tightened housing-loan credit standards during Q2 2026 and that demand for housing loans declined markedly.
These conditions can make purchasing more difficult even when households have adequate income.
Down Payment Is a Major Difference Between Renting and Buying
One of the biggest barriers to purchasing is not the monthly payment.
It is the amount of money required before the purchase is completed.
Buyers may need funds for:
- Down payment
- Mortgage fees
- Legal costs
- Registration or transfer charges
- Taxes
- Property inspection
- Moving
- Initial repairs
Renters usually face much smaller upfront costs.
This can make renting more accessible even when a household could theoretically manage the monthly mortgage payment.
Ownership Has Costs Beyond the Mortgage
A fair comparison should never compare rent with mortgage principal and interest alone.
Homeowners may also need to pay:
- Property taxes
- Home insurance
- Service or association fees
- Maintenance
- Repairs
- Utilities
- Renovations
- Selling costs
Zillow's rent-versus-buy methodology specifically incorporates ownership expenses including taxes, insurance, maintenance and closing costs when comparing the financial paths of renters and buyers.
Renting Provides Greater Flexibility
Financial calculations are important, but housing is also a lifestyle decision.
Renting may suit households that:
- Expect to move soon
- May change jobs
- Are uncertain about location
- Want fewer maintenance responsibilities
- Need greater mobility
- Want to preserve cash
Buying generally involves higher transaction costs and may be less suitable for a short expected stay.
Buying Can Provide Greater Stability
Home ownership may offer benefits that are difficult to express through a simple spreadsheet.
These may include:
- Greater housing stability
- More control over improvements
- Less exposure to lease renewal decisions
- Potential equity accumulation
- Greater ability to personalise the home
Whether those benefits justify the additional cost depends on the household.
Housing Supply Influences Both Choices
Renting and buying do not operate as completely separate markets.
A shortage of homes can increase both property prices and rents.
The OECD's July 2026 housing research describes persistent housing affordability pressure across many OECD and EU countries as partly the result of an imbalance between housing demand and supply, influenced by construction costs, labour shortages, financing costs and land-use restrictions.
Greater housing supply can improve choice in both rental and ownership markets.
Price-to-Rent Ratios Can Help With Market Research
One useful market-level measure is the price-to-rent ratio.
It compares property prices with rental costs.
The OECD notes that the price-to-rent ratio can provide an indicator of the relative economics of housing ownership, although it should not be treated as a complete personal rent-versus-buy calculation.
A relatively high price-to-rent ratio may indicate that purchasing is expensive compared with renting.
But financing, taxes and expected ownership duration still matter.
The Decision Changes With Your Time Horizon
For someone expecting to live somewhere for one or two years, purchasing may involve too many transaction costs to recover comfortably.
For someone planning to remain for a decade or longer, buying may have more time to absorb:
- Purchase costs
- Selling costs
- Market fluctuations
- Maintenance expenses
and potentially benefit from:
- Mortgage principal repayment
- Property appreciation
- Longer-term housing stability
This is why expected length of stay should be one of the first questions in a rent-versus-buy analysis.
What Should Renters Compare?
A renter should consider:
- Monthly rent
- Rent increases
- Deposit
- Utilities
- Parking
- Insurance where applicable
- Moving frequency
- Flexibility
If renting creates substantial monthly savings compared with buying, consider what happens to those savings.
The comparison becomes much more meaningful if the renter deliberately saves or invests part of the difference.
What Should Buyers Compare?
A potential buyer should estimate the complete cost of ownership.
That includes:
- Down payment
- Mortgage payment
- Interest
- Taxes
- Insurance
- Service charges
- Maintenance
- Repairs
- Purchase costs
- Selling costs
- Opportunity cost of invested capital
Buyers should also consider how long they expect to own the property.
Prozameen 2026 Rent vs Buy View
The evidence available through September 2026 suggests that renting currently offers a stronger short-term affordability position in many expensive housing markets.
In the United States, typical rental costs are materially below the monthly cost facing new home buyers.
European data also shows renting is currently more affordable than purchasing in many major cities.
However, the decision changes when the time horizon becomes longer.
Buyers can build equity, while renters may build wealth by investing money that would otherwise have gone toward higher housing costs and a down payment.
The most important factors to evaluate are:
- Local rent
- Local property price
- Mortgage rate
- Down payment
- Ownership expenses
- Expected rent growth
- Expected length of stay
- Transaction costs
- Financial flexibility
There is therefore no universal winner between renting and buying.
The stronger choice depends on the household, the location and the time horizon.
Research Methodology
This report is a Prozameen synthesis of publicly available housing-market research.
Primary sources include:
- Zillow Research
- Realtor.com Economic Research
- JLL
- Eurostat
- European Central Bank
- OECD
The report combines evidence from several markets to explain broader rent-versus-buy dynamics.
U.S. statistics should not be treated as global averages, and European statistics should not automatically be applied to other regions.
Research Period
January 2026 to September 2026
Latest major data incorporated: September 2026
Important Information
Housing prices, rents, mortgage rates, taxes and transaction costs vary significantly between countries, cities and individual properties.
Prozameen provides this research report for general informational and educational purposes only.
Frequently Asked Questions
4 questions answeredYou May Also Like
Explore more research and insights from Housing Market Research