
Global Property Price Trends Report 2026
Property prices in 2026 are telling very different stories depending on where you look.
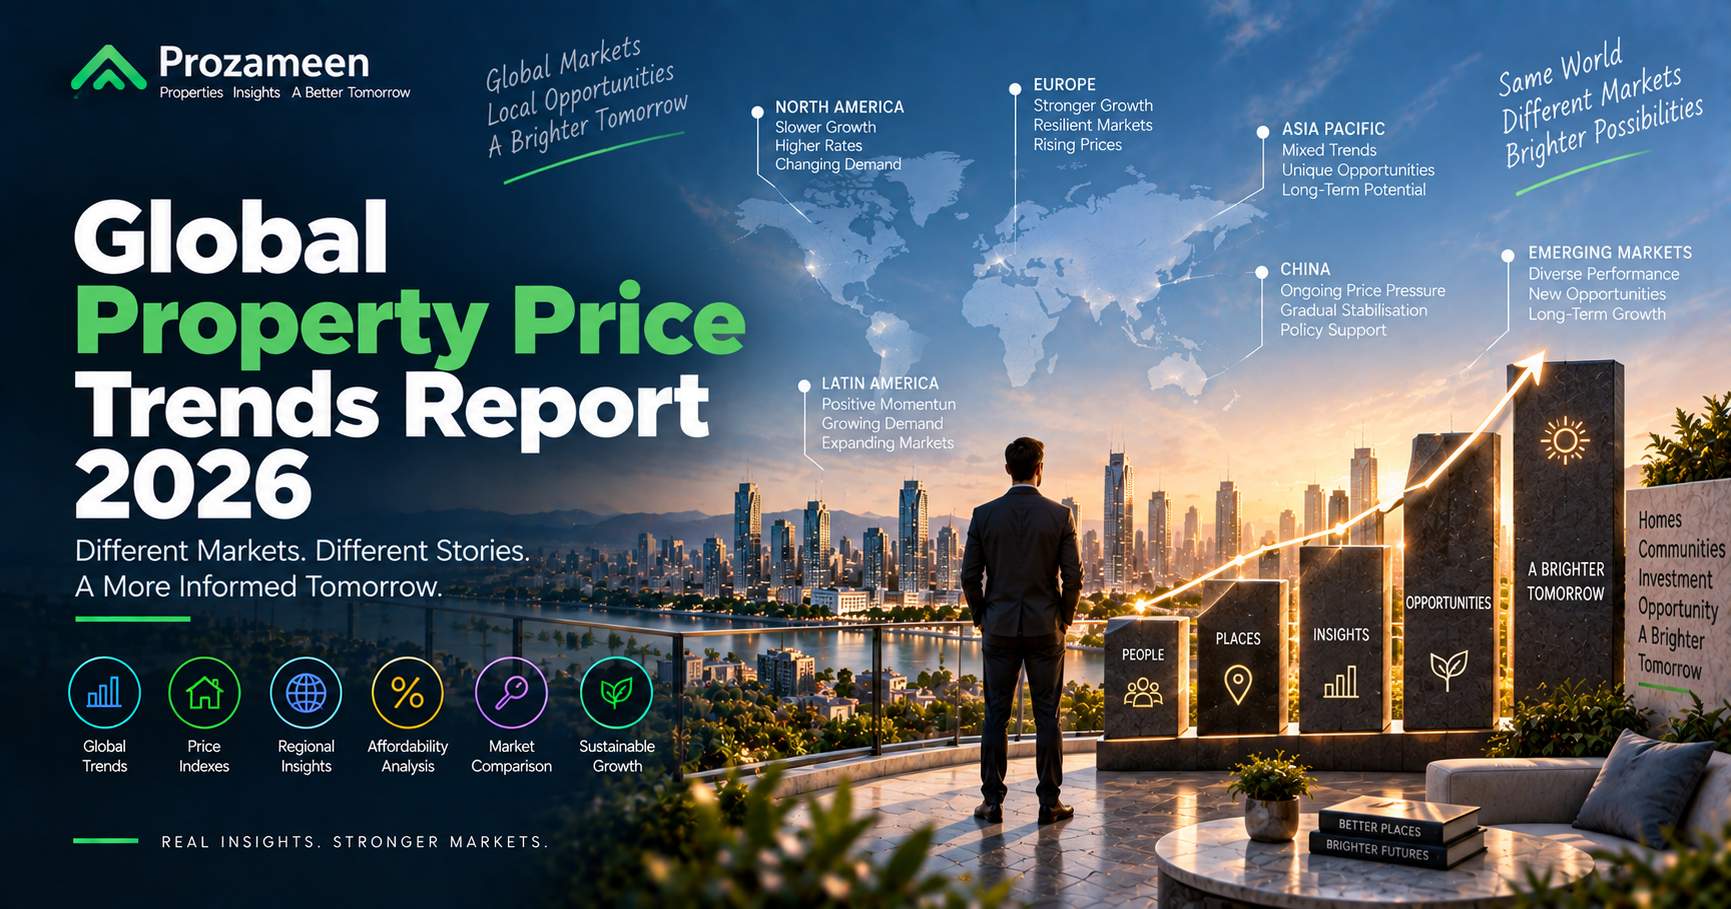
Some European markets are still recording strong price growth. U.S. home prices are rising more slowly. China continues to face property-price pressure, while several emerging and developed markets are moving in completely different directions.
The Prozameen Global Property Price Trends Report 2026 examines these differences and explains why there is no single global property-price trend.
Executive Summary
The major property-price themes in 2026 include:
- Real global residential prices declined during the first quarter of 2026
- Nominal global prices still increased when inflation was not removed
- European housing markets remain comparatively strong
- U.S. house-price growth has slowed significantly
- China continues to experience falling residential prices in many cities
- Latin American markets have shown stronger real price growth
- Australia remains comparatively resilient
- Affordability continues to limit how quickly prices can rise
- Local housing supply remains a major driver of price differences
- Buyers should avoid using global averages to judge an individual market
The most important message is simple:
The global property market is becoming increasingly fragmented.
Global Real House Prices Declined
The Bank for International Settlements reported that real global residential property prices fell 1.2% year over year in the first quarter of 2026.
Real prices remove the effect of consumer-price inflation, making them useful for understanding whether housing values are increasing faster or slower than general prices.
The same BIS data showed that nominal global house prices actually increased by approximately 1.7% year over year during Q1 2026.
This distinction matters.
A property price can rise in money terms while still declining after inflation is considered.
Advanced Economies Were Almost Flat in Real Terms
Across advanced economies, real residential property prices declined approximately 0.2% year over year in Q1 2026.
However, that average hides major differences.
The BIS reported:
- Australia: approximately +6%
- Euro area: approximately +2.6%
- United States: approximately -2%
- United Kingdom: approximately -2%
- Canada: approximately -7%
These are inflation-adjusted changes rather than nominal headline house-price movements.
Europe Remains One of the Stronger Regions
European property prices have generally remained resilient in 2026.
Eurostat reported that house prices increased 5.1% across the European Union and 4.7% across the euro area between Q1 2025 and Q1 2026.
Compared with the previous quarter, prices increased 1.2% in the EU and 1.0% in the euro area.
This means European housing prices were still rising at a meaningful pace even while the broader inflation-adjusted global index was falling.
Property Price Growth Varies Dramatically Within Europe
Even within Europe, there is no single market trend.
Eurostat reported some of the strongest annual Q1 2026 increases in:
- Portugal: +17.8%
- Bulgaria: +14.8%
- Slovakia: +14.4%
Finland was the only EU member with available data to record an annual decline, at approximately -2.0%.
The BIS inflation-adjusted data similarly identified Portugal as one of the strongest residential markets globally during Q1 2026.
These differences show why European buyers should analyse individual countries and cities rather than treating Europe as one property market.
U.S. House Prices Are Still Rising, but Slowly
U.S. home prices have not collapsed, but price growth has moderated substantially.
The Federal Housing Finance Agency reported that U.S. house prices increased 2.1% between Q2 2025 and Q2 2026.
Prices increased only 0.3% between Q1 and Q2 2026, indicating relatively slow quarterly growth.
This nominal increase contrasts with the BIS inflation-adjusted measure, which showed U.S. real residential prices down around 2% year over year in Q1.
Both figures can be correct because they measure prices differently.
Why U.S. Price Growth Has Slowed
Several factors are limiting U.S. property-price growth.
These include:
- High mortgage rates
- Reduced buyer purchasing power
- Increasing housing inventory
- More seller price reductions
- Affordability constraints
- Greater buyer negotiating power
Higher financing costs can weaken demand even when households still want to purchase homes.
This is one reason transaction activity can slow without producing a dramatic national price decline.
The UK Is Experiencing Modest Growth
The UK housing market also shows significant regional variation.
The Office for National Statistics reported that average house prices in England increased 1.1% year over year to £293,000 in July 2026.
During the same period:
- Wales increased 2.6%
- Scotland increased 2.3%
- Northern Ireland recorded a much stronger 9.2% annual increase in Q2 2026
These figures demonstrate substantial differences within a single national housing market.
China Remains a Major Source of Global Price Weakness
China continues to play an important role in the global property-price decline.
BIS data showed real residential prices in China down approximately 7% year over year in Q1 2026.
China's National Bureau of Statistics reported continued year-over-year declines across many of the 70 large and medium-sized cities it tracks in August 2026, although the pace of decline was narrowing in several city categories.
This distinction is important.
The market may be experiencing slower price declines without yet returning to broad-based price growth.
Shanghai Shows That China Is Not One Market
China's national property weakness also hides differences between cities.
Official August 2026 data showed new-home prices in Shanghai approximately 3.0% higher than one year earlier, while Beijing's corresponding index was around 2.3% lower.
Many other cities continued to report year-over-year declines.
This is another example of why city-level analysis is essential.
Emerging Markets Are Also Highly Divided
BIS data showed real residential property prices across emerging market economies declining approximately 2.0% year over year in Q1 2026.
But the regional picture was dramatically different:
- Emerging Asia: approximately -4.3%
- Latin America: approximately +5.0%
- Other emerging economies: approximately +3.2%
China's large size had a significant effect on the overall emerging-market figure.
Latin America Has Been Comparatively Strong
BIS data showed continued real residential property-price growth across Latin America during Q1 2026.
Examples included approximately:
- Brazil: +5%
- Mexico: +4%
These figures contrast sharply with declining real prices across parts of Asia.
This illustrates how broad labels such as “emerging markets” can hide major regional differences.
Inflation Changes the Property-Price Story
One of the easiest property-market mistakes is comparing nominal price growth across countries without considering inflation.
Suppose property prices rise 4% while consumer prices rise 5%.
The homeowner sees a higher nominal property price, but the property's inflation-adjusted value has actually declined.
This is why Prozameen distinguishes between:
Nominal property prices — the actual price expressed in money.
and
Real property prices — the price after adjusting for inflation.
Both measures are useful, but they answer different questions.
Global Prices Remain Higher Than Before the Financial Crisis
Short-term weakness should also be considered in a longer historical context.
The BIS estimates that real global residential property prices remain approximately 20% above their levels at the end of the 2007–09 Global Financial Crisis.
Since the beginning of the COVID-19 pandemic, however, real global prices have increased by only around 3%.
This demonstrates how much recent inflation has changed the interpretation of nominal property-price increases.
Housing Supply Remains a Major Price Driver
Property prices are affected by more than interest rates.
Supply matters enormously.
Markets where housing construction does not keep pace with household formation, migration or urban growth may continue to experience price pressure even when financing becomes expensive.
Important supply constraints include:
- Limited available land
- Planning restrictions
- Construction costs
- Labour shortages
- Financing costs
- Infrastructure capacity
- Slow development approvals
This helps explain why some high-rate markets continue to experience rising home prices.
Mortgage Rates Affect What Buyers Can Pay
Property prices and mortgage rates are closely connected through affordability.
When mortgage rates increase, buyers may need to:
- Reduce their target property price
- Increase their down payment
- Accept a smaller home
- Move to another area
- Delay purchasing
However, prices do not always fall immediately because sellers may also choose not to list their properties.
This can restrict supply and partly offset weaker demand.
Property Prices and Income Should Be Viewed Together
A home price that appears reasonable in one country may be extremely expensive relative to local household income in another.
The OECD uses the price-to-income ratio as one measure of housing affordability.
It compares property prices with household disposable income and can help show whether home prices are becoming more or less affordable relative to earnings.
For home buyers, local income conditions are often more useful than global property-price rankings.
Property Prices and Rent Also Tell a Story
The OECD also tracks the price-to-rent ratio.
This compares property prices with rental prices and can help show how expensive ownership has become relative to renting.
A high property price does not necessarily mean a poor investment.
Likewise, a low property price does not automatically mean good value.
Investors still need to analyse:
- Rental income
- Operating expenses
- Vacancy
- Financing
- Property condition
- Location
- Future supply
Real Estate Quality Is Becoming More Important
Broader 2026 market research suggests that demand is increasingly concentrated in better-quality real estate.
JLL describes global demand as resilient while also highlighting greater focus on efficiency, building quality, energy availability and operational performance.
This can create different price behaviour even within the same neighbourhood.
Modern, efficient properties may perform differently from older buildings requiring major upgrades.
What Should Home Buyers Watch?
Home buyers should avoid deciding whether a market is expensive based solely on whether prices increased last year.
Instead, examine:
- Local comparable sales
- Price per square metre
- Mortgage rates
- Household affordability
- Property condition
- Local housing inventory
- Days on market
- Price reductions
- Neighbourhood development
The relevant market is usually the specific neighbourhood and property type, not the country average.
What Should Property Investors Watch?
Investors should combine price trends with income analysis.
Important indicators include:
- Purchase price
- Rental income
- Rental yield
- Net Operating Income
- Cap rate
- Vacancy
- Financing costs
- Cash flow
- Future housing supply
- Local economic conditions
Strong past price growth does not guarantee future investment performance.
What Should Sellers Watch?
Sellers should pay attention to current comparable transactions rather than older peak-market prices.
Useful indicators include:
- Recent completed sales
- Active competing listings
- Price reductions
- Buyer demand
- Mortgage affordability
- Time on market
A national market can still be rising while a particular neighbourhood or property category is weakening.
Prozameen 2026 Property Price View
The evidence available through September 2026 suggests that the global residential market is experiencing divergence rather than a universal boom or crash.
Europe remains comparatively strong.
The U.S. is experiencing slower nominal growth and slight real-price weakness.
China continues to weigh heavily on global averages.
Parts of Latin America and Australia remain comparatively resilient.
The key property-price themes to watch through the remainder of 2026 are:
- Mortgage rates
- Housing inventory
- Household income
- New construction
- Inflation
- Buyer affordability
- Local migration
- Economic growth
- Rental demand
- Property quality
The most useful conclusion for buyers and investors is therefore not that “global property prices are rising” or “global property prices are falling”.
Both statements can be true depending on the market being analysed.
Research Methodology
This report is a Prozameen synthesis of publicly available residential property-price research and official statistics.
Primary sources include:
- Bank for International Settlements
- Eurostat
- U.S. Federal Housing Finance Agency
- UK Office for National Statistics
- National Bureau of Statistics of China
- OECD
- JLL
Different sources use different methodologies.
Some statistics are nominal, while others are adjusted for inflation.
Reporting periods also differ by country.
For this reason, figures should be interpreted using the exact geography, methodology and period stated in the report.
Research Period
January 2026 to September 2026
Latest major country data incorporated: September 2026
Important Information
Property-price trends vary significantly between countries, cities, neighbourhoods and property types.
Prozameen provides this research report for general informational and educational purposes only.